Tecon says its animal health business recorded its first loss in 2026, citing VAT policy changes and pressure from the livestock downturn, competition and reduced vaccination by some large customers. First-half vaccine revenue fell 44% year on year to about CNY 270 million (USD 40.5 million), while gross margin remained at 53.08%.
Tecon Biology Co., Ltd. said its animal health business had recorded its first loss since operations began, with the loss occurring in 2026. The company made the disclosure at a briefing on its third-quarter results on 26 October.
Tecon attributed the loss to two factors. Changes to value-added tax policy for biological products had affected profit. Meanwhile, the downturn in the downstream livestock sector, intensifying competition, falling market prices and reduced or suspended vaccination by some large corporate customers had weighed on the animal health business.
“Management is currently allocating more resources to the animal health segment and strengthening its oversight. Going forward, we will focus on products, prioritising a succession of new product launches to support a recovery in performance,” the company said.
Tecon said it was moving from being solely a “product supplier” to a “provider of comprehensive service solutions”. It is adopting a more market-oriented approach to marketing its pharmaceutical business while concentrating resources on developing overseas markets, accelerating overseas registration of key products and expanding abroad through technical cooperation.
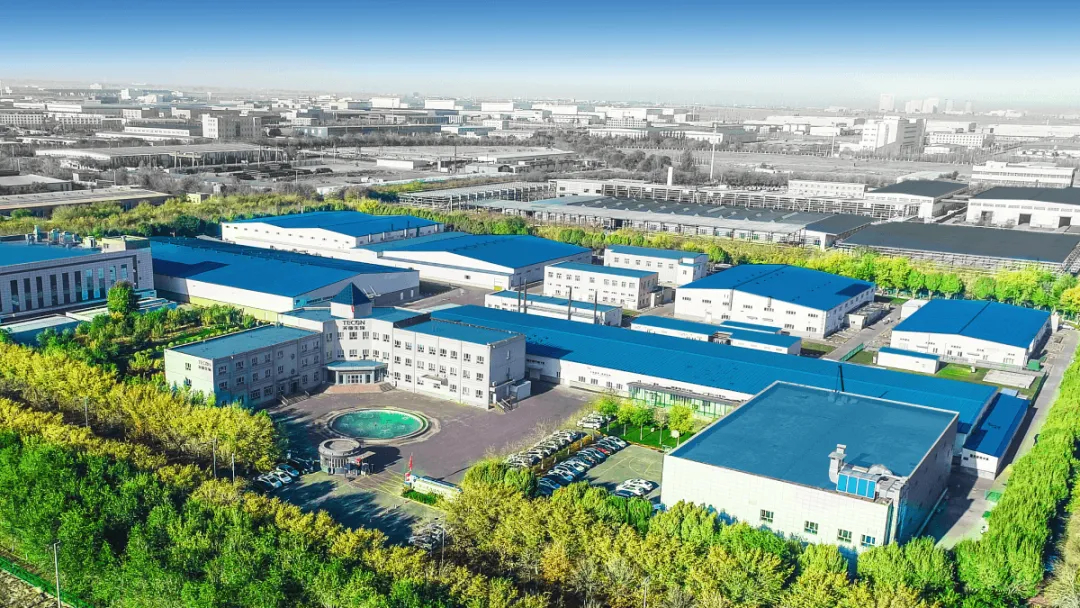
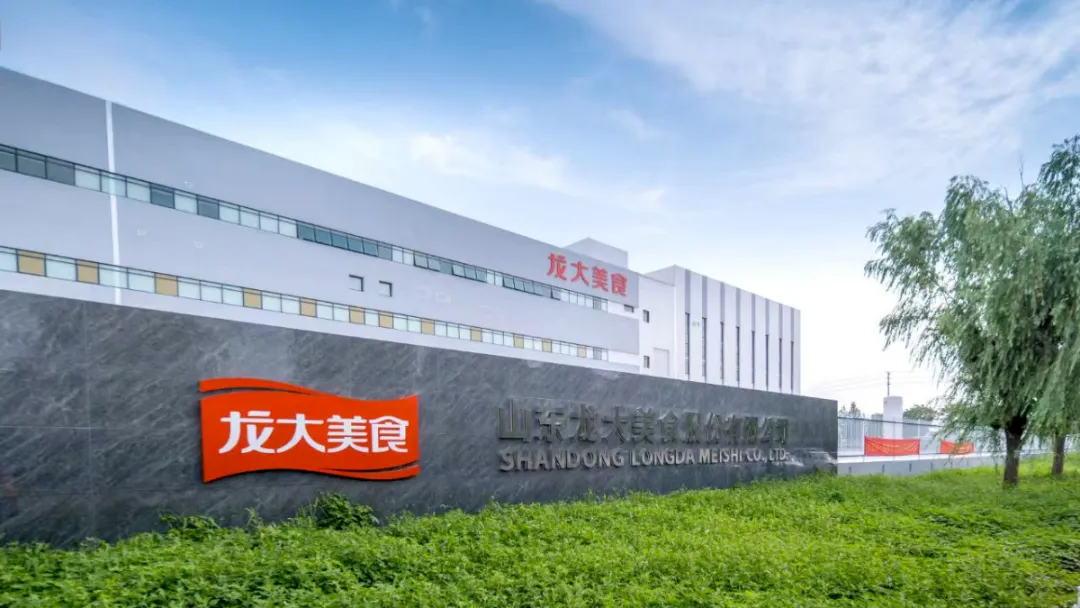
Tecon’s foot-and-mouth disease vaccine production base in Urumqi.
According to the source report, Tecon is the only producer of veterinary biological products in Xinjiang designated by China’s Ministry of Agriculture. It is one of 10 designated foot-and-mouth disease vaccine producers and one of 12 designated avian influenza vaccine producers nationwide. The ministry has also designated it to produce vaccines against classical swine fever, porcine reproductive and respiratory syndrome (PRRS), and peste des petits ruminants (PPR). The company ranks among China’s top 10 veterinary biological product companies.
In the first half of 2026, Tecon’s animal vaccine business generated sales revenue of about CNY 270 million (USD 40.5 million), down 44% year on year and accounting for just 3.24% of total company revenue. Its gross margin remained high at 53.08%, despite falling by 12.81 percentage points from a year earlier.
By comparison, pig farming and feed accounted for about 32% and 28% of Tecon’s first-half revenue, respectively. Their gross margins over the same period were -10.15% and 9.72%.
In the first nine months of 2026, Tecon sold nearly 2.12 million tonnes of feed and marketed nearly 3.02 million pigs. Its overall loss reached nearly CNY 600 million (USD 90.0 million).
Tecon also disclosed that its breeding sow herd had fallen to 191,000 head by the end of September 2026. This comprised 124,000 at Tecon’s own operations and 67,000 at Qiangdu Animal Husbandry. Earlier market estimates had put the respective herds at about 150,000 and 80,000 head.
Tecon’s overall full cost of pig production fell to CNY 11.6/kg (USD 1.74/kg) in September 2026, down further from CNY 11.8/kg (USD 1.77/kg) in June. June was also when Tecon completed the consolidation of Qiangdu Animal Husbandry, which had achieved strong production performance, into its financial statements.
AgriPost.CN – Your Second Brain in China’s Agri-food Industry, Empowering Global Collaborations in the Animal Protein Sector.